When should I first talk to a business broker about selling?
Talk to a good broker 2 to 3 years before you want to sell. They'll show you what buyers will pick apart and who you need on your side to fix it.
October 8, 2026
By Remi Taffin · October 13, 2026
A letter of intent has arrived, and the buyer’s request list already runs several pages. Your books were kept on a cash basis, three technicians are paid on 1099s, and the newest truck is still titled to you personally. None of those issues ends a deal by itself. Each one, though, gives a buyer another reason to question the numbers, delay closing, or lower the price if you haven’t explained it first.
This financial due diligence checklist follows the order buyers and lenders commonly use when reviewing an owner-operated HVAC, plumbing, roofing, electrical, landscaping, or similar service business. It starts with whether the books can be trusted and ends with warranty and litigation exposure. Each area includes the trade-specific failure points that tend to cost money, along with the records worth pulling before a buyer asks for them. The checklist is general information, not legal, tax, or financial advice. For transaction-specific guidance, owners may also want to speak with a California business purchase lawyer.
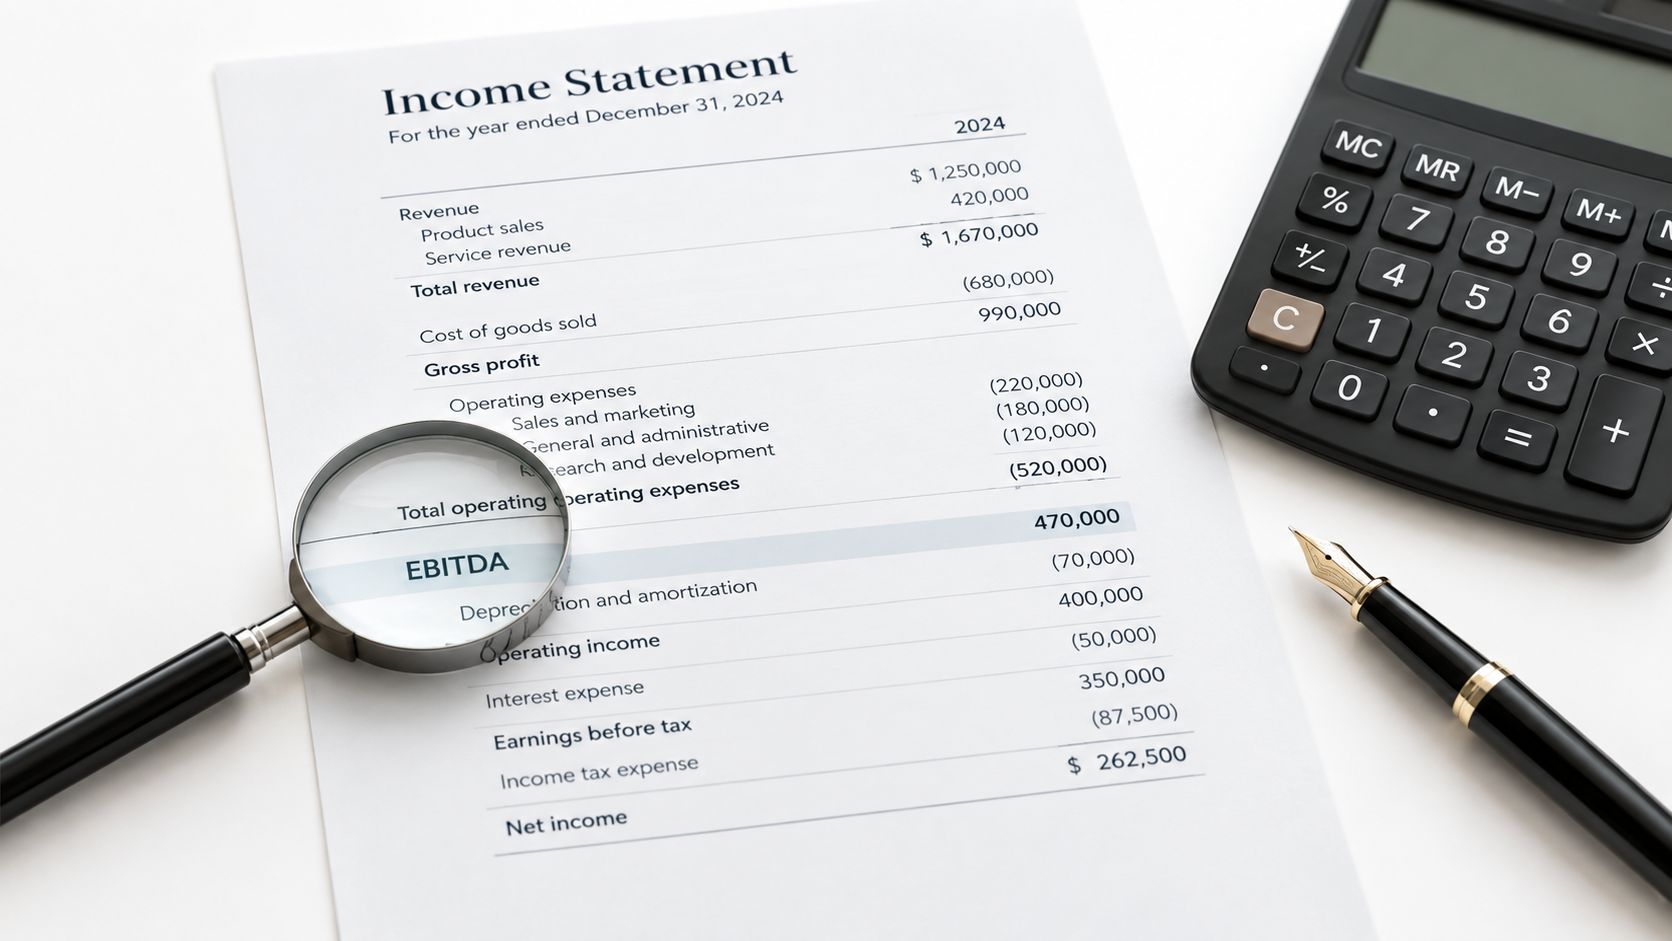
Before discussing price, establish whether the books support the earnings being presented. Tie the income statement, balance sheet, and cash flow reports to bank activity, credit-card statements, invoices, payroll records, and job files. Gaps here can delay a transaction even when the underlying business is sound.
Cash-basis accounting is common in smaller trade businesses, but it can place completed work, unpaid bills, customer deposits, and inventory purchases in the wrong period. Ask your CPA whether the last three years of financial statements can be prepared on an accrual basis. The conversion may identify unbilled work, open payables, deferred revenue, or costs recorded late.
Practical rule: Explain accounting problems before the buyer finds them. Early disclosure frames them as items to correct. A late discovery raises questions about the reliability of every reported figure.
For HVAC and plumbing companies, job costing should separate labor, materials, subcontractors, permits, warranty work, and callbacks. A general contractor also needs current work-in-progress schedules. Otherwise, a margin change may reflect delayed cost entries rather than better pricing or productivity.
Prepare a transaction file with:
A bookkeeping review asks whether records are maintained. Financial due diligence asks whether reported profit can support sustainable earnings and cash generation. Correcting reconciliations and organizing supporting schedules can also help with reducing reconciliation processing time.
Once the reports reconcile, walk the buyer through how completed jobs become reliable monthly reporting.
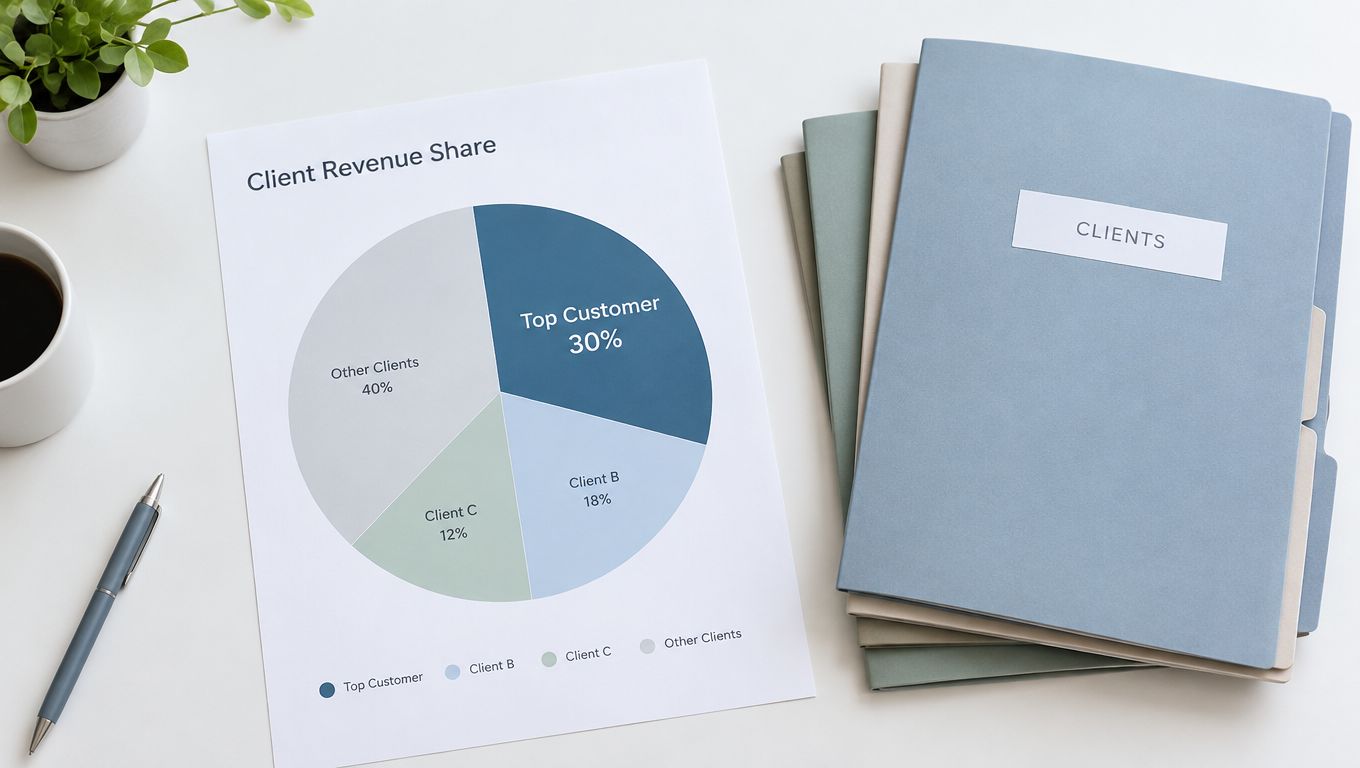
Revenue quality matters more than the top-line total. A buyer will separate one-time emergency calls from maintenance agreements, commercial contracts, installation work, referral work, and revenue that depends on the owner’s personal relationships.
Build revenue reports by customer, service type, salesperson, and month. Then compare the pattern across the last three years. Look for customers who stopped buying, service lines with declining margins, commercial contracts approaching renewal, and accounts where the owner remains the only relationship holder.
Recurring revenue can make planning easier, but it still needs testing. For an HVAC company, a maintenance agreement is more useful when the company can show renewal history, service frequency, pricing, and cancellation reasons. For a roofing contractor, a project backlog is only valuable when signed contracts, deposits, permits, materials, and realistic completion timing support it.
A large customer isn’t automatically a problem. An undocumented relationship is. If one property manager, hospital, builder, or commercial landlord represents a meaningful share of revenue, organize the contract, renewal history, pricing terms, decision-maker information, and service records.
Also identify revenue that could leave with the owner. If customers call your personal mobile number, ask for you by name, or follow you between businesses, the buyer may treat that revenue as less transferable.
Useful records include:
The buyer isn’t only asking whether you produced revenue. The buyer is asking whether the next owner can produce it without rebuilding the sales engine.
Owner compensation is rarely as simple as the salary line. In a family-run landscaping, roofing, or electrical business, the company may pay personal vehicle costs, health insurance, travel, family payroll, discretionary spending, or expenses tied to a related property.
Buyers often normalize these items. An add-back is an expense added back to reported profit because the buyer believes it won’t continue after closing. The buyer will still ask what replaces the owner’s work and what costs remain.
That distinction creates the most common mistake. An owner may remove a salary from the calculation while ignoring the cost of hiring an operations manager, estimator, dispatcher, or general manager. If you currently handle sales, scheduling, collections, customer complaints, hiring, and technical decisions, those responsibilities have economic value.
List every proposed adjustment with the general-ledger account, amount, date, explanation, supporting invoice, and expected treatment after closing. Separate personal expenses from costs the business will still incur. A family member’s payroll may be an add-back if that person performs no ongoing work, but it isn’t an add-back if the person handles dispatch or bookkeeping.
Your CPA should also review the tax treatment of historical personal expenses. A transaction reviewer may accept some adjustments for valuation analysis while still questioning whether the underlying expense was properly reported.
Keep the schedule conservative. Unsupported add-backs can make the entire earnings presentation look aggressive. Buyers tend to trust a smaller list with clear evidence more than a longer list built around judgment calls.
A Quality of Earnings analysis, often called a QoE, tests whether reported profit is accurate, sustainable, and repeatable. It usually rebuilds the financial story from the general ledger, bank deposits, invoices, tax returns, payroll records, customer data, and supporting documents.
The central output is a bridge from reported profit to normalized EBITDA, or to seller’s discretionary earnings for a smaller owner-operated company. That bridge should identify one-time expenses, owner-related costs, accounting errors, unusual revenue, changes in gross margin, and costs a buyer will need to add back after closing.
For a service company, the review must go beyond a spreadsheet. An HVAC business might show strong margins because warranty calls and truck repairs were posted late. A plumbing company might show impressive revenue because a commercial customer accelerated work that won’t recur. A roofing company may have a large backlog that contains low-margin projects or jobs dependent on unresolved permits.
A QoE shouldn’t be frozen at the last year-end. Maintain monthly close packages, a revenue-to-gross-profit bridge, an adjusted EBITDA schedule, customer and service-line concentration, working-capital trends, capital-expenditure history, and a dated post-period-events log. Update the analysis through the latest month before signing so a buyer can’t argue that the old report hides recent deterioration.
Each adjustment should include:
A seller who commissions the work early can explain weaknesses before the buyer frames them as surprises. Read more about what a Quality of Earnings report is before deciding whether an external review fits your situation.
Working capital is the operating capital needed to deliver ordinary revenue. It usually includes accounts receivable, inventory, prepaid expenses, accounts payable, and accrued payroll, while excluding financing items and other items the purchase agreement treats separately.
A working-capital peg is the target level the parties agree the business should deliver at closing. If the business delivers less than that target, the purchase price may fall. If it delivers more, the price may rise. The definition matters as much as the calculation.
Trade businesses create unusual seasonal patterns. An irrigation company may collect differently during the busy season than the winter. A pool-service company may carry customer receivables and supplier obligations that change sharply by month. An electrical contractor may have completed work sitting in receivables while deposits for future projects sit in deferred revenue.
Calculate operating working capital for at least 24 months and identify seasonal highs and lows. Review receivables by age, inventory that no longer turns, supplier terms, customer deposits, accrued payroll, and payables that have been stretched to preserve cash.
An aged receivable isn’t automatically worthless, but it needs evidence. Check subsequent collections, customer disputes, credit notes, and payment history. Clean up uncollectible receivables and obsolete inventory before negotiating the peg, or document why they should remain in the calculation.
The purchase agreement should define each included line item. Work with your adviser and transaction attorney to decide how deposits, deferred revenue, prepaid insurance, accrued bonuses, and unusual receivables will be handled. A clear working-capital peg prevents the closing adjustment from becoming a dispute over definitions.
Enterprise value is not the amount the seller necessarily receives. Net debt means debt and debt-like obligations are deducted from the business value to determine the equity price. The review must include more than the bank loan shown on the balance sheet.
Prepare one schedule for every loan, vehicle note, equipment-financing agreement, line of credit, shareholder loan, lease, lien, and personal guarantee. Add obligations that may not look like conventional debt, such as unpaid bonuses, accrued vacation, deferred compensation, unpaid taxes, customer deposits, deferred revenue, and obligations tied to work scheduled after closing.
A plumbing company with financed trucks should obtain payoff letters early. The payoff amount may differ from the balance on the books because of interest, fees, or a prepayment charge. If the seller owns the building personally, document the lease or sale treatment separately. A buyer needs to know whether the company will continue paying rent, acquire the property, or move.
For every obligation, record:
Customer deposits deserve special attention. If the buyer takes money for installations that haven’t been completed, the buyer may inherit the labor, materials, warranty, and scheduling obligation. The parties need to decide whether the deposit transfers with a corresponding price adjustment or remains the seller’s responsibility.
Tax problems can affect both the price and the structure of a transaction. Review federal and state income taxes, payroll taxes, sales taxes, use taxes, local business taxes, tax notices, payment plans, and open examinations.
The business structure also matters. An asset sale and a stock or membership-interest sale can produce different tax outcomes for the seller and different depreciation benefits for the buyer. A C corporation, S corporation, partnership, and LLC may each require a different analysis. Don’t negotiate the headline price before your CPA models the after-tax proceeds under the available structures.
For trades businesses, sales-tax treatment can become complicated when an invoice combines labor, materials, maintenance, installation, and taxable products. A landscaping company may have different treatment for services and supplied materials. An HVAC company should review how it handles replacement units, parts, labor, maintenance plans, and customer deposits.
Organize filed returns, payment confirmations, payroll filings, sales-tax returns, notices, correspondence, tax-account transcripts, and any voluntary disclosures. Reconcile book income to tax returns and explain material differences.
Don’t conceal a filing gap. Correcting an issue early may still cost money, but it gives you more control over the explanation and the timing. A buyer who discovers it may seek a price reduction, escrow, indemnity, or closing condition.
Tax rules vary by state and transaction structure. Review the plan with a licensed tax professional before signing anything.
Labor is usually the cost that most directly determines whether a service business can deliver its revenue. Buyers review payroll registers, wage rates, overtime, benefits, workers’ compensation, timekeeping, bonuses, vacation accruals, and employee turnover.
The 1099 issue deserves an honest review. A technician who works under the company’s direction, uses company scheduling, wears the company’s branding, performs core work, and depends on the company for customers may create classification risk even if the company issues a contractor form. Review each contractor under the IRS common-law framework and applicable state rules. State tests can differ from federal standards.
A classification correction may reduce reported profit because W-2 payroll brings taxes, benefits, insurance, and administration. That can still improve the sale process by removing a serious buyer objection and giving lenders a more credible labor-cost picture.
Create a confidential employee schedule with role, tenure, pay structure, certifications, skills, and customer responsibilities. Identify the lead technician who knows every commercial account, the dispatcher who keeps the route system moving, and the estimator who holds key relationships.
Retention planning should happen before employees hear rumors. Buyers may want retention agreements, stay bonuses, or transition commitments for essential employees. Also confirm that overtime calculations and time records are accurate under the Fair Labor Standards Act, and review practical workers’ compensation questions with resources such as this Florida LLC workers comp exemption guide.
A service company can appear more profitable when the owner delays replacing trucks, vans, tools, lifts, diagnostic equipment, or shop systems. The buyer sees the missing spending later, often immediately after closing.
Separate maintenance capital expenditures, which keep current operations running, from growth capital expenditures, which support expansion. A roofing company that postpones fleet replacement may report stronger short-term earnings, but the buyer will ask what it costs to replace unsafe or unreliable vehicles. An electrical contractor may also need to replace testing equipment, ladders, trailers, or warehouse systems that are fully depreciated but still essential.
Build a fleet and equipment register with purchase date, mileage or usage, condition, ownership, financing, maintenance history, and expected replacement timing. Compare depreciation to actual maintenance spending. Low depreciation doesn’t prove that the equipment is healthy.
The buyer isn’t buying the fixed-asset register. The buyer is buying the ability to complete tomorrow’s jobs without an immediate cash drain.
Confirm that every company vehicle and major tool is titled to the business. If the newest truck is titled personally, document its transfer, lease, or exclusion before the buyer finds it. Obtain realistic replacement estimates and decide whether to fix the issue, disclose it, or reflect it in the price.
The final financial review is about costs that may arrive after the sale. Review workmanship warranties, product warranties, callbacks, customer complaints, insurance claims, threatened litigation, regulatory notices, license issues, permit disputes, and unresolved settlement discussions.
Track warranty work by job, crew, service type, date, cost, and cause. A roofing contractor may discover that several callbacks came from one installation crew or one material batch. An HVAC company should distinguish ordinary service calls from repeated failures tied to installation quality. A pool contractor needs records for cracks, leaks, completion disputes, change orders, and unpaid balances.
Buyers also want to know whether the reserves are adequate. If the company has promised long-term workmanship coverage but has no history of claims by job, the buyer may assume the worst. That can produce a larger escrow, a special indemnity, a holdback, or a price reduction.
For every known issue, record the facts, estimated exposure, insurance coverage, responsible party, customer communications, and proposed resolution. Disclose known claims early. Nondisclosure can create a larger problem than the original repair or dispute.
Check that licenses, permits, insurance policies, bonds, and warranty obligations can transfer as required. Some obligations stay with the seller. Others move with the assets or customer contracts. Your attorney should determine how the purchase agreement allocates them.
Cybersecurity also belongs in this final risk review because a breach can create remediation, notification, insurance, and customer costs. Freshfields reported that 78% of surveyed global deal professionals believed cybersecurity was not examined closely or specifically quantified in M&A diligence, while 83% said a discovered prior breach could cause a deal to be abandoned. See the Freshfields cybersecurity and M&A report for the survey context.
| Area | 🔄 Implementation complexity | ⚡ Resource requirements | ⭐ Expected quality/importance | 📊 Expected outcomes | 💡 Ideal use cases & tips |
|---|---|---|---|---|---|
| Financial Statement Integrity and Accounting Systems | High, may require accrual conversion and reconciliations | CPA time, accounting software, bookkeeping cleanup (moderate–high) | ⭐⭐⭐⭐⭐ | Reliable monthly P&L/BS; faster diligence; fewer post-closing disputes | Essential pre-sale step; reconcile monthly and keep documentation |
| Revenue Quality and Customer Concentration | Medium, data segmentation and customer analysis | CRM/billing data, time to analyze, contract review (moderate) | ⭐⭐⭐⭐ | Clear view of recurring vs. one‑time revenue; identifies concentration risk | Useful for subscription/membership models; document top customers and renewals |
| Owner Compensation and Add-Back Normalization | Medium, requires market comps and documentation | Payroll records, invoices, market salary benchmarks (moderate) | ⭐⭐⭐⭐ | Defensible normalized earnings; potential valuation uplift if supported | For owner-operated firms; track personal expenses and estimate replacement salary |
| Quality of Earnings (QoE) Analysis | High, deep independent rebuild of earnings | External accounting firm, 3+ years of records (high) | ⭐⭐⭐⭐⭐ | Defensible normalized EBITDA; speeds negotiations; reduces surprises | Best for mid‑sized or contested deals; start 6–12 months before market |
| Working Capital Analysis and the Working Capital Peg | Medium, monthly analysis and legal definition | Accounting time, advisor/attorney to draft peg (moderate) | ⭐⭐⭐⭐ | Agreed peg reduces price disputes; clarifies cash needs and seasonality | Crucial for seasonal trades; model 12‑24 months of monthly WC before closing |
| Net Debt and Debt‑Like Items | Medium, compile loans, liens, and debt‑like items | Lender payoff letters, loan schedules, legal review (moderate) | ⭐⭐⭐⭐ | Accurate equity proceeds modeling; avoids last‑minute surprises | Prepare payoff letters early; list guarantees and lien details |
| Tax Compliance and Tax Exposure | High, tax filings review and sale-structure modeling | CPA/tax attorney, multi-year returns, state nexus review (high) | ⭐⭐⭐⭐⭐ | Minimizes indemnities; optimizes after‑tax proceeds; avoids delays | Model asset vs. stock sale early; clear payroll/sales tax records |
| Payroll, Worker Classification, and Labor Costs | High, classification and wage/hour compliance | Payroll registers, HR/legal review, benefits records (moderate–high) | ⭐⭐⭐⭐ | Reduces wage and classification risk; may change normalized earnings | Audit 1099s vs. W‑2s before listing; document key‑employee roles and retention |
| Capital Expenditures, Fleet, and Equipment Condition | Medium, asset inventory and capex analysis | Fixed‑asset register, inspections, replacement cost estimates (moderate) | ⭐⭐⭐⭐ | Reveals maintenance vs. growth capex; affects FCF and purchase price | Create fleet schedule; compare depreciation to actual replacement spending |
| Warranty Reserves, Callbacks, Litigation, and Contingent Liabilities | Medium–High, claims history and legal exposure review | Claims records, insurance files, attorney review (moderate–high) | ⭐⭐⭐⭐ | Quantified contingent liabilities; better reserve sizing; fewer escrows | Track callbacks by job/crew; disclose known claims early and settle when practical |
Start with the books because every other figure depends on them. A buyer can’t evaluate revenue quality, owner add-backs, working capital, debt, taxes, payroll, or fleet needs with confidence if the underlying statements don’t reconcile.
Then assign an owner and a deadline to every open item. The owner might be you, your CPA, your bookkeeper, your attorney, your insurance adviser, or a department manager. Keep a dated issue log that records the question, supporting document, decision, and remaining risk. That log becomes useful when the buyer asks why a number changed or why an old liability was treated a certain way.
A controlled data room helps once the review begins. A 2023 survey of 150 senior U.S. investment-banking executives found that 80% had added more technology to their M&A due-diligence process during the prior 12 to 24 months. The same survey gave virtual data rooms 51% of respondents’ top-two votes for the most valuable technology, narrowly ahead of project-management software at 50%. Those findings support a practical choice for smaller owners: organize documents in indexed folders with clear filenames, version control, request status, reviewer comments, and an audit trail instead of sending scattered attachments by email. Read the Acquiom and SRS due-diligence survey for the cited results.
The economic stakes can be material. A 2024 Journal of Finance study reported that mergers took an average of 134 days to complete after public announcement and estimated that inefficient due diligence could impose an economic loss equal to 4% to 8% of total deal value. The study also reported a 20.5% one-year probability of deal failure from exogenous causes in its model. That’s why diligence should start before price and terms feel final, not after the buyer has already formed a negative view. See the Journal of Finance research on mergers and due diligence for the methodology and context.
Owners who finish this review before going to market control the story. Buyers who run it before signing know what to negotiate, what to fix, and what risks need protection in the purchase agreement. If you want help finding a business broker whose past sales match your industry and size, The Owner’s Shortlist offers a free, no-obligation introduction by phone at (321) 320-7239 or through theownersshortlist.com.
The Owner’s Shortlist offers a free, plain-language introduction to a specialist whose past work fits your service business, industry, and size. If you’re preparing the financial records for a sale or want to understand which diligence issues may affect value, visit The Owner’s Shortlist to start a private conversation with a real person.
Tell us your situation. We'll connect you with a specialist who works with owners like you. One conversation, no sales pressure.
Found this useful?
Add The Owner's Shortlist as a preferred source and get our articles highlighted in Google Search results.
Add to Preferred SourcesTalk to a good broker 2 to 3 years before you want to sell. They'll show you what buyers will pick apart and who you need on your side to fix it.
October 8, 2026
Compare 10 business transfer lawyer options for sales, succession, family transfers, and smaller deals, with questions, fee models, and red flags.
October 5, 2026
Interest rates, inflation, the headlines. None of it matters as much as owners think. Here's what actually determines whether now is the right time to sell.
October 5, 2026
A tuck-in is when a buyer folds your business into one they already own, instead of running it on its own. Here's what that means for price and your team.
September 29, 2026